Jacksonville Claim Payment Delays and Legal Options
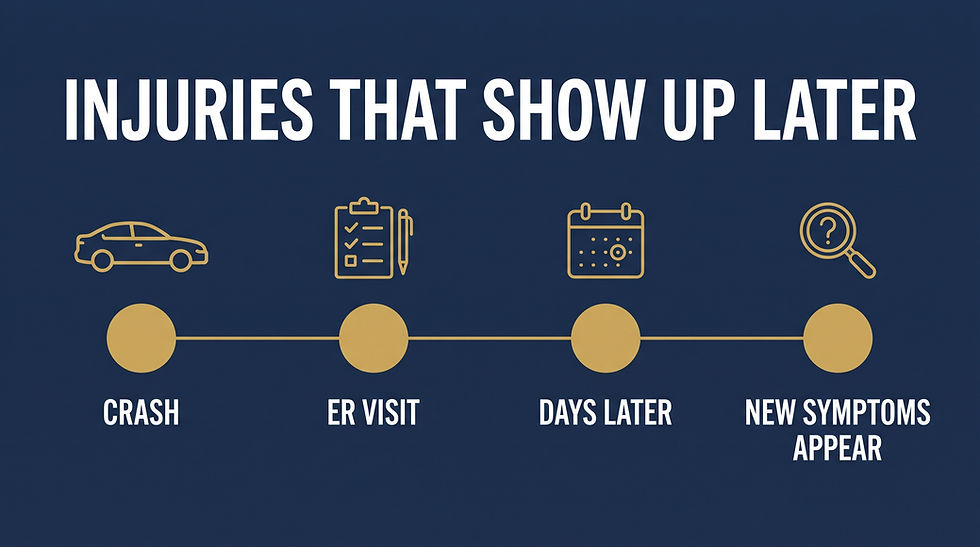
You are hurt, your car is in the shop, and the medical bills keep landing on the kitchen table. Rent is due, kids need school supplies, and the holidays are coming fast, and the insurance company keeps saying your payment is still “processing.” Every week that passes, the pressure gets heavier.
You should know that delay is a weapon. When that check does not come, you start thinking about putting co-pays on credit cards, skipping treatment, or accepting the first small offer just to breathe for a month. The company on the other side knows that. They count on it.
Insurance companies want you to believe you must “just be patient.” Meanwhile, your life keeps moving:
Rent and mortgage payments
Car loans and insurance premiums
Childcare and groceries
End-of-year and holiday costs
When you stall, they win. When you track, push, and enforce deadlines, you take back power. Our job as Jacksonville accident lawyers is to attack delay tactics head-on and stop insurers from dragging you through months of financial pain for their own gain.
How Florida Insurance Deadlines Really Work Day by Day
Most injury claims move through the same core stages, no matter how complicated an insurer tries to make the process sound.
First, you report the claim. After that, you should see:
Initial contact from an adjuster within a short period
Requests for basic records and documents
An investigation window where they review your injuries and damage
A payment or denial decision within a reasonable time
Florida law and insurance regulations, including Florida Administrative Code Rule 69O-166.024, put real clocks on some of those stages, so this is not open-ended:
Florida’s claims rules call for an insurer to acknowledge and respond to your communications within 14 days
PIP benefits become overdue if the insurer does not pay within 30 days after receiving notice of the covered loss and the amount
Once you agree to a settlement, the insurer must pay within 20 days
Most Florida negligence lawsuits must be filed within two years of the crash
Some of these rules depend on the type of claim. The 30-day PIP rule (Florida Statutes § 627.736) applies to your own no-fault benefits, and the 20-day rule (§ 627.4265) applies once you have a settlement agreement in place. Serious injury claims against the at-fault driver’s insurer usually take longer to investigate and value, and the length of that review depends on the injuries and the damage. But endless silence is not normal. When a company keeps “reviewing” without asking you for anything new, that is not careful work. That is stalling.
Florida law also expects insurers to handle claims in good faith, and an insurer that fails to settle when it could and should have done so can be held responsible under Florida’s bad faith statute. Late-year claims run into one more predictable excuse: “holiday delays.” Adjusters take vacations, offices claim they are “short staffed,” and files sit while your bills do not. The answer is uncompromising: lock in timelines early, keep everything documented, and refuse to accept “it is the holidays” as a free pass to push your life to the side.
Delay Tactics Exposed: How Insurers Stall Your Money
We see the same tricks over and over. They are not accidents. They are strategies.
Some of the most common delay moves include:
“We just need one more document” after you already sent everything twice
Rotating adjusters and “file transfers” that restart the clock every time
A sudden “special review” the moment you push back on a low offer
Long gaps with no follow-up until you call and complain
These patterns show up in auto, truck, motorcycle, bicycle, and trip‑and‑fall claims across Jacksonville and Northeast Florida. Different types of crashes, same slow‑pay playbook.
Here is the psychology behind it. Insurers know people will:
Feel worn down after months of waiting
Worry about credit scores and collection calls
Stress over holiday gifts, travel, and family plans
Accept less than their claim is worth just to stop the pressure
We have seen this countless times. Adjusters act friendly, then stretch out the process until you feel cornered. Don’t let them tell you this is “just how it works.” When you know the signs of stalling, you can attack them instead of taking the hit.
Tracking Every Day: Your Personal Claims War Log
If the insurer is running a time game, your answer is simple: you build a war log. You turn every day of delay into evidence.
Start with a claims journal. Nothing fancy, just relentless consistency:
Date and time of every call
Who you spoke with
What they said and what they promised
Any deadline or follow-up they mentioned
Next, save every single thing they send or say:
Emails, letters, texts, and portal messages
Voicemails and call screenshots
Copies of forms you complete
You also keep a running medical and billing log:
Dates of each doctor visit, therapy session, and test
Every bill, co‑pay, and out‑of‑pocket cost
Collection notices or past‑due warnings
Set up a simple but disciplined system so you stay in control:
Create one digital folder and one paper folder dedicated to your claim
Use a calendar to mark follow‑up dates and expected responses
If they promise an update, set a reminder in 7 to 10 days to chase it
Here is why this works. A clean, time‑stamped record turns “he said, she said” into hard facts. It exposes broken promises, shifting stories, and useless delays. When Jacksonville accident lawyers step in with that timeline in hand, we can hit back hard, because every excuse can be checked against your record.
When Jacksonville Accident Lawyers Force Real Action
Delay crosses the line from slow to abusive when:
You get no real response for weeks, even after direct follow‑ups
The company claims it is “investigating,” but has not asked you for anything new
A lowball offer suddenly appears after months of silence
That is when a tough lawyer changes the game.
Here is what we do in that situation:
Send formal demand letters with clear terms and firm deadlines
Push the claim up the chain, away from low‑level stalling
Use your documented timeline to show a pattern of delay and pressure tactics
Data and documentation are weapons. When we present a clean log that shows every call, every broken promise, every “we are still reviewing” message, it undercuts the insurer’s story. Stalling stops looking safe for them. It starts looking dangerous.
Here is the truth: the sooner we get involved in a Jacksonville claim, the faster timelines tighten. Once the insurer sees you are not alone, not confused, and not willing to accept games, real movement starts. That is not a favor. That is the result of pressure backed by proof.
Stop Waiting on Empty Promises: Take Back Control Now
Waiting quietly is exactly what insurance companies want. They want you patient, tired, and second‑guessing yourself. You beat that by tracking every day, calling out every stall, and building the record we can use to secure the justice and compensation you deserve.
If you are injured in Northeast Florida and your claim is stuck in “processing,” start now. Gather your paperwork. Write out your timeline. List every broken promise and every delay excuse. Then put that war log to work with Jacksonville accident lawyers who know how to expose stalling tactics and fight relentlessly for faster, stronger results and the compensation you are entitled to.
Protect Your Rights And Start Your Recovery Today
If you were hurt in a crash and are unsure what to do next, our experienced Jacksonville accident lawyers are ready to review your case and explain your options. At Moore, we guide you through every step, from dealing with insurance companies to pursuing the full compensation you may deserve. Reach out today so we can evaluate your situation and provide clear next steps, or contact us to schedule a free consultation.